
Isaac Brekken/Getty Images for WE tv
Category Archives: marriage advice
Kendra Wilkinson Asks Fans for Dating and Sex Advice After Hank Baskett Split
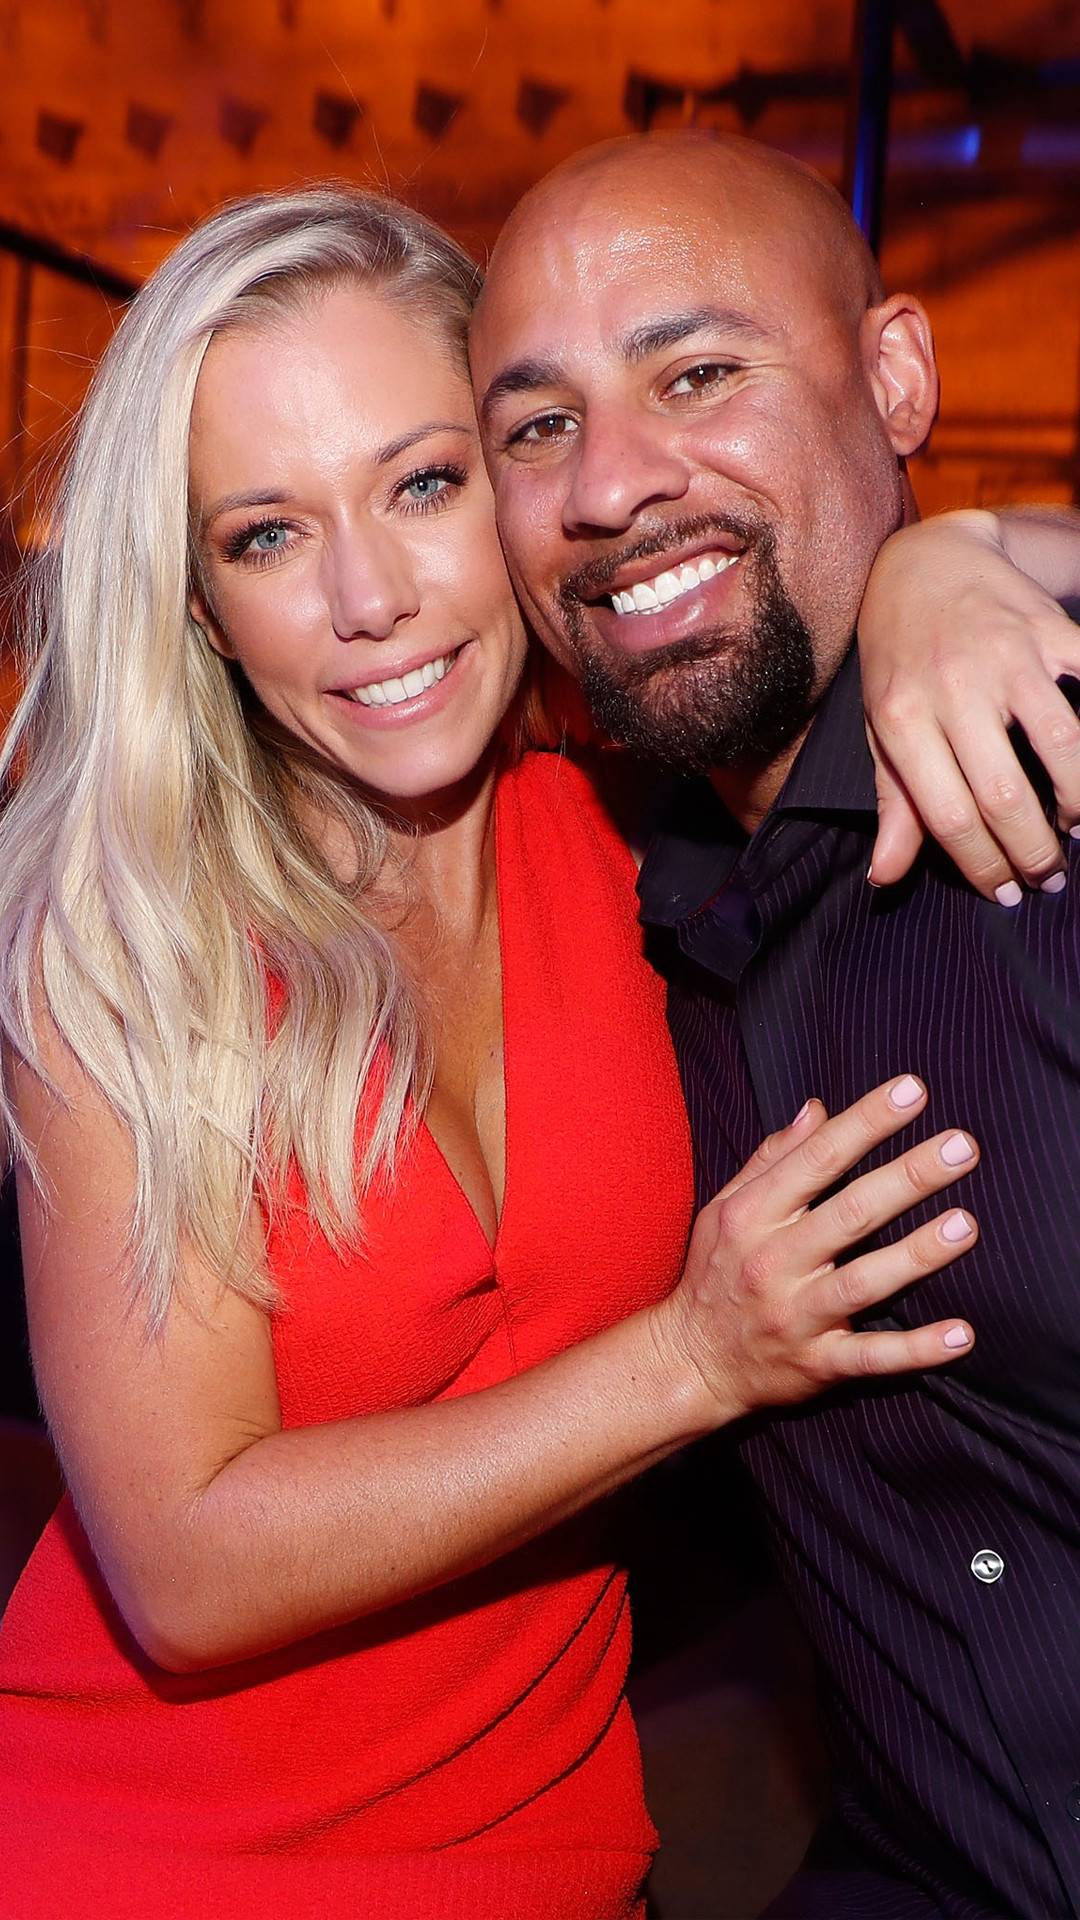
One month after filing for divorce from Hank Baskett, Kendra Wilkinson is seeking dating and sex advice.
In early April, Kendra confirmed the split on social media, telling her Instagram followers, “Today is the last day of my marriage to this beautiful man. I will forever love Hank and be open but for now we have chosen to go our own ways.” Shortly after, E! News learned that the reality star had officially filed for divorce from her husband after eight years of marriage.
Now, Kendra’s asking her fans for relationship advice via Twitter.
“What’s your opinion… do i start dating/sex now or give myself more time?” Kendra tweeted on Monday, May 14. “My heart is broken but i have needs. Lmaoooo #gimmelovin #notgettingyounger #33hereicome.”
What’s your opinion… do i start dating/sex now or give myself more time? My heart is broken but i have needs. Lmaoooo 😂 #gimmelovin #notgettingyounger #33hereicome 💀😏🤨🕸👵🏻
— Kendra Wilkinson (@KendraWilkinson) May 14, 2018
All out of batteries. It’s time my friend https://t.co/lajoV9tPLn
— Kendra Wilkinson (@KendraWilkinson) May 14, 2018
Where do i go? Lmaooooo 😭 https://t.co/EN9q90cqzL
— Kendra Wilkinson (@KendraWilkinson) May 14, 2018
“Use the vibrator for a while and get your head straight,” one Twitter user replied. “Unfortunately I have back slid and given some to the ex cause the choices in men worry me.”
Kendra replied, “All out of batteries. It’s time my friend.”
Another Twitter user told Kendra, “Get out there and do the damn thing. You still got youth on your side, use it!”
“Where do i go?” Kendra asked. “Lmaooooo.”
Before asking for advice on Monday, Kendra wished her followers a belated happy Mother’s Day.
Hope u all had a great Mother’s Day. Mine was amazing. This will be one I remember forever. My babies know how to make me smile n it’s as simple as good quality time n living in the moment. 😃🙏🏻
— Kendra Wilkinson (@KendraWilkinson) May 14, 2018
“Hope u all had a great Mother’s Day,” Kendra tweeted. “Mine was amazing. This will be one I remember forever. My babies know how to make me smile n it’s as simple as good quality time n living in the moment.”
Kendra and Hank have two kids together, 8-year-old Hank Baskett IV and 3-year-old Alijah Baskett.
Don’t miss E! News every weekday at 7 and 11 p.m.
Katrina Bowden, Whose Anniversary Is May 19, Offers Advice to Meghan Markle and Prince Harry
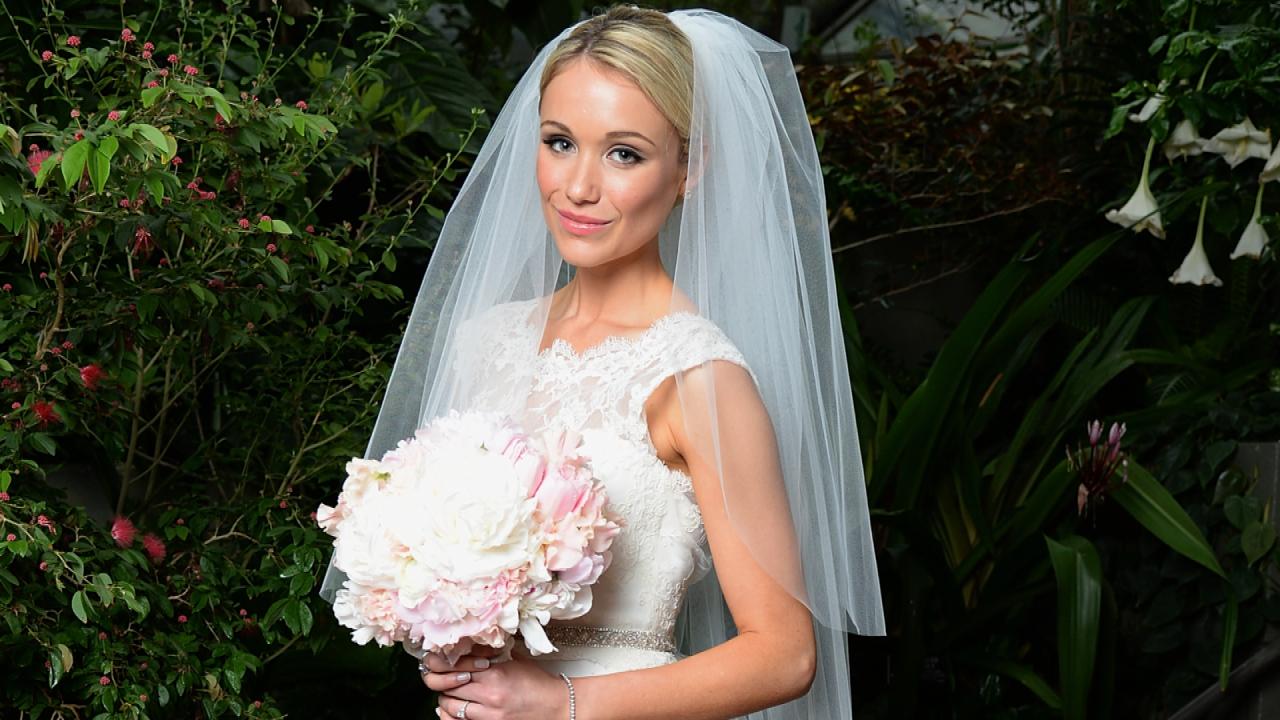
“30 Rock” actress Katrina Bowden and her musician husband, Ben Jorgenson, are offering their own marriage advice to Prince Harry and Meghan Markle ahead of the royal wedding.
The soon-to-be royal couple will actually share an anniversary with Bowden and Jorgenson, who married on May 19, 2013.
Speaking to InsideEdition.com, Bowden and Jorgenson offered their own tips to marital bliss.
“Unload the dishwasher,” Bowden said jokingly.
The couple said they understand the pressures of being in the spotlight, and emphasized the need to keep some things in their relationship private.
“Keep everyone, A, intrigued by you because you’re not sharing everything and, B, it’ll just keep the magic alive a little bit,” Bowden said.
Jorgenson said it’s also important to just be able to relax and enjoy each other’s company.
“Those are the favorite parts of my day when we get to just hang out and watch TV and be in pajamas,” he said.
But maybe the most important piece of advice from Bowden to Harry?
“I think every guy, no matter who it is who is getting married, should just remember to always cherish the woman and just treat her like she’s special,” Bowden said.
Meghan and Harry will tie the knot this weekend at Windsor’s St. George’s Chapel.
RELATED STORIES
More Royal Wedding Details Emerge With Just a Week to Go Before Prince Harry Marries Meghan Markle
Meghan Markle’s Father Seen Delivering Flowers at His Ex-Wife’s Home Ahead of Royal Wedding
Meghan Markle and Prince Harry Recreated in Mock Royal Wedding Made of Nearly 60,000 Legos
On Marriage and Money: A CFP's Perspective

While wedding planning is a time for picking flowers, colors and cake flavors, there are some more important things you should be discussing. A newly engaged financial adviser details how to handle those tough conversations.
For those in a committed relationship or recently engaged, there’s lots of online advice about how to get through wedding planning and still have a wedding. From the “irritable bride/groom syndrome” to the planning-induced insomnia and worries about family drama to come, there’s probably an article out there to help you deal with the issue and retain a measure of sanity.
SEE ALSO: Do Not Let Money Ruin Your Marriage
Unfortunately, there isn’t much advice about using the engagement period to build a lasting foundation for a successful financial life together. Even though money consistently tops lists as a frequent source of conflict in a relationship, the blueprint for talking about it is curiously absent. As someone who happens to be in the financial advice field and is recently engaged, I’d like to close the gap and start the conversation.
When a new prospect is interested in financial advice, I begin by compiling “a total client profile.” Through guided discovery, I learn about their values, goals, important relationships and assets. When I am speaking with a husband and wife, some of my questions elicit completely different responses. If married people can’t see their shared financial world through the same lens, is there hope for those who are merely engaged?
I believe there is. However, it begins with having several critical conversations before you walk down the aisle.
Advertisement
First, full disclosure
Building a life together requires you and your partner to work with the same set of building bricks or assumptions. That means being clear on what each one of you brings to the union. You might share tidbits of financial history here and there (such as the fact that your Visa card is maxed out and you cannot charge honeymoon flight tickets until you pay it off), but that “organic” sharing is too disjointed and unreliable to give you a full picture.
Therefore, every couple needs to create a dedicated space for the pre-wedding money conversation. In doing so, it is critically important to get the timing and the setting right. Some people prefer a walk out in nature, where they aren’t facing each other across the table and the changing scenery encourages openness to different perspectives. Others are most comfortable broaching the subject on a Sunday morning over coffee. No matter what, choose a private space where you can speak freely without the fear of being interrupted.
Next, lay out the ground rules. Here are some ideas to get you started:
- Tell the truth.
- Don’t hide things.
- Hold a safe space with no judgment.
- Cover all aspects of financial well-being, including past debt, loans, savings, commitments to support family members, pre-existing business interests, etc.
Here is a real-life example of how failing to do this might backfire. I was conducting a discovery conversation with a well-off couple. As we were talking about relationships, I raised a question: “Which family member relationships are most important to you?” The gentlemen talked about the fact that his mom was getting older, and how they may need to begin supporting her financially. The wife nodded along with approval, clearly aware of this situation.
Advertisement
When I addressed the same question to her, she mentioned that her younger sister had been struggling financially. “I’ve been sending her a couple of thousand dollars every month,” the wife shared in a matter-of-fact manner. “I thought you knew this!” Judging by the wide-eyed look on the husband’s face, this expense (that added up to tens of thousands of dollars over the past year alone) was news to him. An argument ensued, to which I was an uncomfortable witness.
Lesson learned: Don’t assume anything when it comes to money. Talk it through. No matter what you learn, do your best to manage your reactions and responses. Emotional outbursts and exclamations along the lines of “How could you!” won’t move you to a happier place. Focus on the next constructive step. If a compromise isn’t possible, table the issue for another time. Above all, be patient. Getting on the same page regarding money is a life-long process.
Next up, talk about financial goals
Here is a good illustration of how two people living together can have very different definitions of financial goals. I recall sitting at a kitchen table in the home of some prospective clients, working on the client profile. “In dollar figures, how much money do you need or want?” I asked. Simultaneously, the wife replied “$2 million” just as her husband answered “$200,000.” They looked at each other in disbelief and dug in their heels defending “their number.” The irony that a husband and a wife sharing a household could have two “mental budgets” that are different by a factor of 10 was completely lost on them.
My advice? Talk to your partner about financial goals before you get to the financial adviser. Here are some common mistakes that I see on this front.
Advertisement
Mistake No. 1: Too much focus on creating “our” goals and not enough acknowledgment of individual goals. Yes, you are creating a family unit and merging some of your finances, but “my goals” and “your goals” are still relevant. If you are wondering about the degree of alignment in this department, consider having each partner write out financial goals in “mine,” “yours” and “ours” columns. Do this independently, then compare the lists focusing on mismatches.
Mistake No. 2: Allowing one person to hold all the keys. It’s not unusual to see one partner being more comfortable with managing money, whether thanks to temperament, experience or training. Even if you aren’t the money-savvy half of the couple, you don’t have the license to step out of all money matters. On the flip side, no matter how good you are with money, it’s not a good idea to take over. Find a way to capitalize on natural fit and talent while keeping everyone informed. You might consider holding monthly or quarterly “family money” check-ins, or maintaining a shared file with a central inventory of all accounts, bill payment passwords, etc.
Mistake No. 3: Failing to acknowledge that their partners have different money styles. Perhaps the husband comes from a modest background where every dollar was stretched, while the wife grew up on an unlimited, no-questions-asked allowance. By facing the fact that you have different habits and styles, you may engineer a temporary “role switch” where the free-wheeler is in charge of the family budget for a month. Trying on each other’s attitudes and roles can give you new insights and appreciation for the unique gifts you each bring to the table.
See Also: 3 Common Money Myths You Probably Believe
Finally, talk about life planning
Procrastinating on life insurance and estate planning is normal and common. Virtually everyone I talk to believes they have decades ahead of them to get it done. No one likes to think about the possibility of serious illness, disability or death. When you are planning a wedding, those topics might seem morbid and unnecessary. However, waiting too long can leave your family struggling to get a handle on finances at a time that already stretches their capacity for decision-making. If you delay action on any life planning area, put a firm reminder on your calendar for when you will pick up the conversation. Don’t let it slip through the cracks.
Advertisement
Aside from procrastination, another common mistake I see on the life-planning front is younger couples skimping on life and disability insurance for the stay-at-home parent. Premiums for disability or life insurance might look like an “optional” expense, but those policies can be invaluable if the family must begin to pay for childcare, housekeeping, etc. in the event that the stay-at-home parent becomes sick or dies.
Money conversations for young couples
Let’s be honest: Money conversations can be tough, especially for those who have not had the best parental modeling around finances. Many couples find that an independent voice of reason can guide them through the obstacles, serve as an accountability partner, and mediate the discussion. If you are feeling stuck or unsure where to begin, talk to your financial planner.
Finally, consider re-framing ongoing conversations about money. To build a solid future together, you cannot stop at “having the talk” once. Too many couples only look at finances when there is external pressure — not enough money to pay the rent or cover an unexpected large expense. As a result, they reinforce the experience of money conversations being stressful, limiting and disempowering.
Instead, consider shifting the conversation from “oh no, we have a money problem” to “what do we have to look forward to together?” Instead of having family budget meetings, have life-planning meetings. Talk about what you want to do together, whether it’s a trip to attend a friend’s wedding in Hawaii or a vacation in Europe. Dream about your future home. Reflect on what experiences will make your life together full, joyful and exciting. That places money right where it belongs — in a critically important “support player” role that doesn’t dominate decisions.
See Also: House Hunters: Learn from My Rookie Mistakes
Comments are suppressed in compliance with industry guidelines. Click here to learn more and read more articles from the author.
This article was written by and presents the views of our contributing adviser, not the Kiplinger editorial staff. You can check adviser records with the SEC or with FINRA.
I asked a top relationship psychologist for his 3 best pieces of advice about marriage
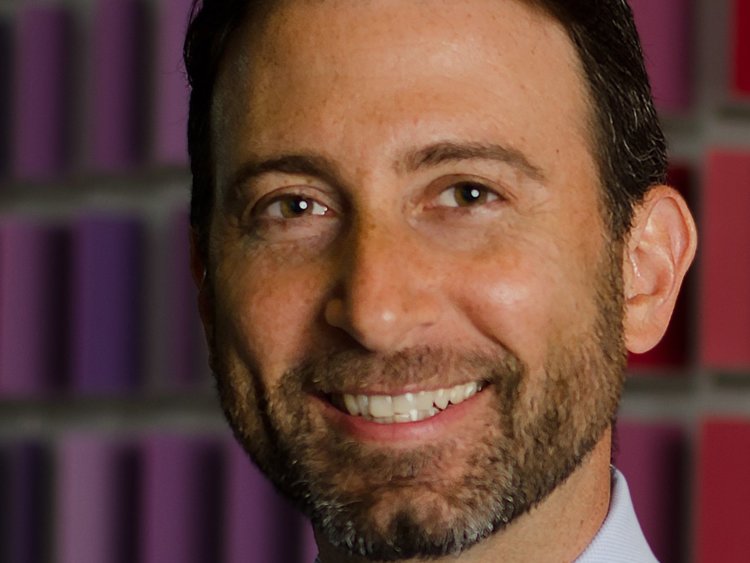
Consider it the “choose-your-own-adventure” version of marriage. Eli Finkel pictured. Courtesy of Penguin Randomhouse
When I interviewed relationship expert Eli Finkel about his new book “The All-or-Nothing Marriage” last year, I was one month away from being a bridesmaid in two of my best friends’ weddings, and two months away from getting married myself.
That is to say: Every question I asked Finkel that day in September stemmed partly from a desire to sate our readers’ curiosity, but — let’s be real — mostly from a desire to sate my own curiosity about what life would really be like after I said, “I do.”
Finkel, who is a psychologist at Northwestern University and a professor at the Kellogg School of Management, didn’t exactly leave me hopeful that my friends and I would all live happily ever after. But he did leave me with some practical tips for making marriage easier when it inevitably gets tear-your-hair-out hard.
During those times, Finkel said, couples can use one of three strategies to strengthen their relationship:
1. Work on the marriage as much as possible
This first option, Finkel said, is for couples who “really want this highly intensive sort of marriage, this extraordinary sort of marriage that is available today.” The kind of marriage in which your partner fulfills the role of soul mate, passionate lover, best friend, and so on.
That means you and your partner have to spend a lot of time together, working through whatever issues you have, and pay a lot of attention to the relationship as it evolves. If you choose this option, making the marriage as strong as it can be is a top priority in your life.
2. Use ‘love hacks’
“Love hacks” are pretty much what they sound like. It’s Finkel’s term for “quick and dirty” strategies to make your marriage just a little bit happier. Best of all, you don’t need your partner’s help to use them.
This is a good option for people who are consumed with something else in their lives besides the marriage: a baby, a medical emergency, a crisis at work.
One example of a love hack is simply re-interpreting your partner’s annoying behaviors. For example, when they show up late to dinner, instead of assuming they’re a jerk who doesn’t care about the family, you assume instead that they hit traffic on the way home from work.
Another example is trying to see at a conflict between you and your partner from the perspective of a neutral third party who wants the best for both of you.
Finkel said of this option: “It won’t take a terrible marriage and make it a spectacular marriage, but it will strengthen the marriage, especially during those periods where you don’t really have the time or the resources to invest in the marriage completely.”
3. Adjust your expectations
This is the option that Finkel “wishes people would consider more seriously”: asking less of your marriage.
He said, “If you find yourself chronically disappointed in one element of your marriage, or in a subset of elements of your marriage, one of the really good ways of dealing with that is to think about: Is it really essential that I try to meet this need in particular through the marriage?”
In some cases, the answer might be a resounding “yes.” In other cases, the answer might be “maybe,” or “not really.” Finkel gave two examples: You like to have philosophical debates and your partner doesn’t. You like to play tennis and your partner doesn’t. Can you find a friend or a coworker to meet these needs for you?
It’s about letting go a little bit, about investing in some relationships other than your marriage.
Here’s Finkel again: “Find those places where the demands you’re placing on the marriage are clearly exceeding the amount that the marriage can actually meet. Just take off some of the demands.”